
A Strange Thought at the Gas Station
It was a thought that suddenly occurred to me while filling up my tank. South Korea doesn’t produce a single drop of crude oil, so why do the earnings reports of oil refiners take up the top headlines of economic news every time? If it were semiconductors or automobiles, it would make sense. I’ve wondered for a while how an industry that doesn’t even extract its own raw materials manages to maintain its spot as the country’s third-largest exporter.
The answer was surprisingly simple. South Korea doesn’t just buy and resell crude oil; it buys crude oil, transforms it into completely different products, and sells them. This difference is bigger than you might think.
More Than Half of the 2.85 Million Barrels Daily Are Exported
South Korea imports an average of 2.85 million barrels of crude oil per day. Since one barrel is 159 liters, that’s an enormous amount, but only about 40% of it is actually consumed domestically. The remaining 60% is refined into products like diesel, gasoline, jet fuel, and naphtha, then loaded onto ships and sent abroad.
Why is this surprising? Usually, when we say a country is “highly dependent on oil,” it sounds like it consumes a lot of energy, but South Korea’s case is different. In fact, among the world’s top 10 oil-consuming nations, only three—Japan, South Korea, and Germany—are not oil-producing countries. Among them, South Korea’s oil dependency relative to GDP is twice that of Japan and four times that of Germany. Looking only at these numbers, it might seem like a country that overconsumes energy, but it is actually closer to a processing trade hub that receives crude oil, turns it into high-value-added products, and distributes them worldwide.
Why Use Middle Eastern ‘Low-Quality’ Oil?
Crude oil prices vary depending on its composition. Light oil, which is light and has few impurities, is expensive, while heavy oil, which is viscous and high in sulfur, is cheap. 70% of the crude oil South Korea imports is from the Middle East, and 99% of that passes through the Strait of Hormuz. However, there is a reason why Korean refiners insist on using this low-cost heavy oil.
It is about $4 per barrel cheaper than American light crude, and South Korean refining facilities are designed from the start to highly decompose and refine heavy oil. Converting these facilities for light oil would require shutting down the plants for at least six months to a year. With conversion costs this high, companies don’t touch them unless absolutely necessary. In the end, ‘facilities that have to use cheap raw materials’ led to ’technology that best handles cheap raw materials,’ which became a barrier to entry that other countries cannot easily follow. At first, I thought this was ironic. That using low-quality raw materials isn’t a weakness, but rather the basis for competitiveness.
Why the U.S. Buys Korean Oil Instead of Using Its Own
This is where it gets really interesting. Since the shale revolution, the U.S. has become the world’s No. 1 oil producer, pumping 13 million barrels per day. Yet, it still imports 6.6 million barrels of crude oil and refined products from abroad every day. You might wonder why a country overflowing with oil would need to import any, but there are two reasons.
One is that U.S. refineries have become outdated, with no new plants built in nearly 50 years. The other is the Jones Act, enacted in 1920. Because this law mandates that transportation between U.S. ports must be handled by ships built in the U.S. and owned/operated by Americans, the maritime freight cost to move crude oil from Texas to California becomes much more expensive than international rates. Therefore, for the U.S. West Coast, it is cheaper to buy Korean refined products across the Pacific than to refine domestic crude. In a sense, a law made 100 years ago is dictating current Pacific trade routes.
This structure is most dramatically visible in the jet fuel sector. South Korea is the world’s No. 1 supplier, holding about 30% of the global jet fuel market, and 70% of the jet fuel the U.S. imports from abroad comes from South Korea. If South Korea were to stop exporting jet fuel overnight, one in every three commercial aircraft worldwide would be grounded. At this point, the term ‘monopoly’ is not an exaggeration.
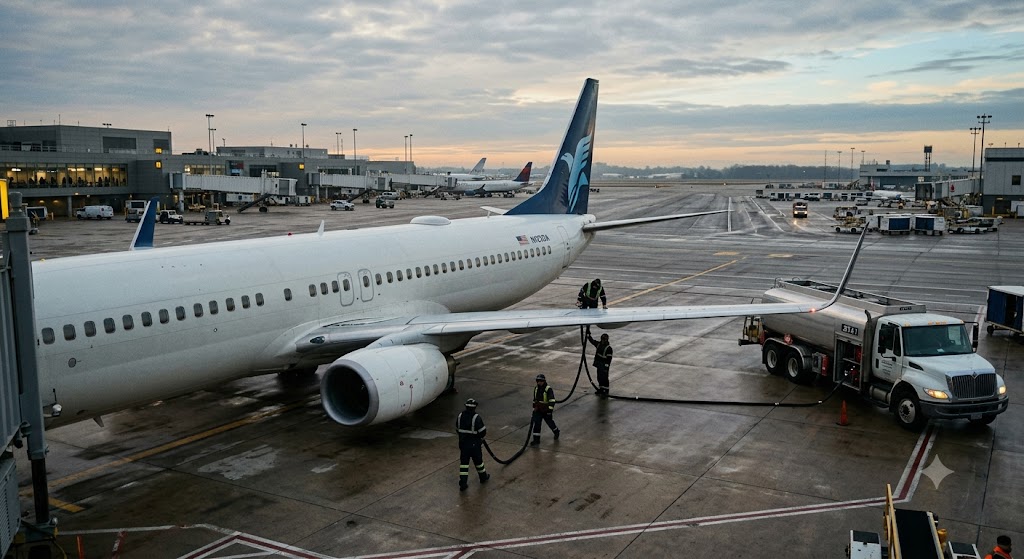
Japan lacks its own refining capacity and imports products from Korea, even having signed an emergency supply agreement, while Australia and New Zealand have closed their own refineries and rely heavily on Korean imports. The choices made by these neighboring countries show that calling South Korea an oil refining powerhouse is no exaggeration.
Looking at the Numbers
Here are the figures, which might seem scattered when explained in words, gathered at a glance.
Enough to Lend Even Our Reserves to Others
It’s not just about refining capacity. South Korea’s petroleum product production capacity is the 5th largest in the world, following the U.S., China, Russia, and India, and we have about 146 million barrels of strategic petroleum reserves—enough for 208 days—stored in nine stockpiling bases in areas like Ulsan and Yeosu. What’s interesting is that we lease some of these storage facilities to Middle Eastern oil-producing countries—on the condition that South Korea can use them first in an emergency. The fact that a country without a single natural resource is storing oil for oil-producing nations felt like the roles were reversed when I first heard it.
This structure wasn’t built overnight. After experiencing two oil shocks in 1973 and 1979, the government pushed the oil refining industry as a national strategic industry. As a result, the four companies—SK Innovation, GS Caltex, S-Oil, and HD Hyundai Oilbank—have secured world-class production efficiency. Today, refined petroleum products are Korea’s third-largest export item, following semiconductors and automobiles.
What’s Different from Singapore or Rotterdam?
When you think of refining hubs, Singapore or Rotterdam in the Netherlands also come to mind. They are similar to Korea in that they don’t produce crude oil but make a living through refining and re-exporting. However, they differ in scale and facility characteristics. Singapore acts more as a transshipment and storage hub due to its location at the logistics bottleneck of the Strait of Malacca, while Rotterdam is more of a refining base targeting the European domestic market. On the other hand, South Korea has an exceptionally high proportion of ‘upgrading/cracking’ facilities that turn low-quality raw materials into high-quality finished products. This means we are specialized not just in receiving and refining crude, but in turning low-grade raw materials into high-grade products. The scale of investment in these upgrading facilities is precisely why latecomers find it difficult to catch up in a short period.
It’s also worth noting the concept of ‘refining margins.’ This refers to the profit left over after a refiner buys crude oil, makes it into products, and sells them. In a structure where low-cost heavy oil is imported and high-priced products are extracted, this margin widens significantly. It’s essentially buying raw materials cheaply and selling finished products at international market prices. However, since refining margins fluctuate every quarter depending on international oil price trends and facility utilization rates, this also explains why refiners’ earnings are so volatile.
A Lifeline Hanging on a Narrow Strait
Of course, this structure is not without weaknesses. The fact that 99% of the Middle Eastern crude oil imported by Korea passes through the Strait of Hormuz means that the moment this narrow strait is blocked, the entire raw material supply line could be shaken. The recent 59% jump in crude oil market prices during the Middle East conflict clearly demonstrated this risk. While the government kept consumer prices around the 1,800 won range by releasing stockpiles and inducing price caps, this is merely a buffer and does not eliminate the fundamental path risk.
It’s not that there are no alternative routes at all. Theoretically, there are ways to increase American light crude or increase the proportion of oil from other regions. However, as mentioned earlier, facility conversion alone takes over six months, and American oil is structurally disadvantageous due to transport time and costs. In the end, because this structure is almost impossible to replace in the short term, the Hormuz risk is not just an ‘occasional event’ but an ongoing variable that the industry must live with.
When Ulsan and Yeosu Shake, the Regional Economy Shakes
The weight of this industry is also confirmed outside of export statistics. Ulsan and Yeosu are cities where a significant portion of the local economy revolves around oil refining and petrochemical complexes. If the utilization rate of one refinery drops or large-scale facility investments are delayed, the impact ripples through partner companies, logistics, and service sectors. Looking at the nation as a whole, it can be summarized by the statistic that the refining industry is a top-3 export item, but at the regional level, this is not just an industry—it is the foundation supporting the entire livelihood of the area. When discussing the competitiveness of the refining industry, if you only look at export amounts and ignore the weight placed on the local economy, you are only seeing half the picture.
How Long Will This Structure Last?
Every time international oil prices have fluctuated due to the recent Strait of Hormuz risk, the fact that domestic oil prices didn’t rise as much as market prices was likely the result of this infrastructure and policy buffers working together. However, it is difficult to conclude that this structure will last forever. Variables like the speed of the shift to electric vehicles, the possibility of reinvestment in U.S. refining facilities, and discussions on amending the Jones Act are all in play. For now, it seems honest to say that it is a ‘structure that won’t be easily shaken for the time being.’
One more point to consider is that this competitiveness is the result of a deliberate national design. It was the government that designated the refining industry as a strategic sector and pushed for facility investment only after experiencing two oil shocks in the 1970s. If we say now that ‘Korea was always good at oil refining,’ this process is erased. Considering that we didn’t just view the lack of resources as a disadvantage, but instead chose to compete through technology that handles low-cost raw materials—leading to our current 30% share of the jet fuel market—the direction of that process is more striking than the result itself.
References
- Middle East energy analysis by Professor Park Hyun-do, Sogang University Euro-MENA Institute
- Korea National Oil Corporation (KNOC) crude oil import statistics
- Korea Petroleum Association (KPA) refining industry status report
- Ministry of Trade, Industry and Energy petroleum/energy supply and demand statistics
- U.S. Energy Information Administration (EIA) Petroleum & Other Liquids data
- IEA Oil Market Report
- Korea International Trade Association (KITA) import/export statistics
- Business reports of SK Innovation, GS Caltex, S-Oil, and HD Hyundai Oilbank
- Public disclosure regarding S-Oil Saudi Aramco equity investment
- Policy analysis regarding the U.S. Jones Act (Merchant Marine Act of 1920)
- Korea Gas Corporation and Korea National Oil Corporation stockpiling base operation status
- International Air Transport Association (IATA) jet fuel supply and demand data
- Korea Customs Service import/export trade statistics
- Bank of Korea export proportion by industry statistics
- OPEC and EIA global oil production capacity ranking data