
If you achieved every life plan you set 15 years ago but feel no joy, who was that plan really for?
This happens because the plan was based on an assumption of perfect prediction, rather than a Nassim Taleb-style allocation that keeps 85~90% of assets in safe havens like government bonds or deposits, while placing the remaining 10~15% in high-risk opportunities with limited losses.
Let’s take a hypothetical person, A.
In their early 30s, A listed goals in order: promotion to executive, buying a specific apartment, and traveling the world after retiring at 60.
Now in their mid-40s, A has crossed off more than half the list, but none of the remaining items spark any excitement. The list remains the same, but the person who wrote it and the person A is today are entirely different.
This article explores the Barbell Strategy as a tool to bridge that gap.
What is the Barbell Strategy and how do you set the ratios?
The Barbell strategy is an allocation method where you keep your assets only at the two extremes—‘very safe’ and ‘very aggressive’—while leaving out the ambiguous, medium-risk assets. It is named after the gym equipment, as the weight is concentrated at both ends.
In his book The Black Swan, Taleb explains that during his time as a trader, he allocated 85~90% of his assets into extremely safe instruments like U.S. short-term government bonds, and the remaining 10~15% into a series of small, high-risk bets.
- The Safe End (85~90%): Assets like cash, savings deposits, or short-term government bonds where the principal remains stable even if the market crashes. In South Korea, if you use savings deposits for this portion, you can use the Financial Services Commission announcement as a baseline: as of September 1, 2025, the deposit insurance limit has increased to 100 million KRW in principal and interest per person, per financial institution (as of October 2026).
- The Aggressive End (10~15%): Bets like startup equity, small-scale speculative assets, side projects, or learning skills unrelated to your main job. These are bets that, even if most fail, could change your life if one succeeds. The amount should be small enough that your daily life remains unaffected if you lose it.
You can see why this structure is ‘Antifragile’ by looking at the profit-loss profile.
In the worst-case scenario, your losses are capped at 10~15%, but the upside is uncapped.
Even if the market shakes violently, your 90% remains intact, turning a crash from a survival issue into an opportunity to fill your aggressive end at a discount.
Why the Barbell Strategy is necessary: The future ‘you’ is different from the current ‘you’
The biggest reason we need a structure that doesn’t rely on prediction is that we underestimate how much we change.
Psychologists Quoidbach, Gilbert, and Wilson called this phenomenon the End-of-History Illusion in a 2013 Science paper that surveyed 19,000 people aged 18 to 68. People admitted their personalities, values, and tastes had changed significantly over the past decade, yet they predicted they wouldn’t change much over the next ten years. This was true regardless of age.
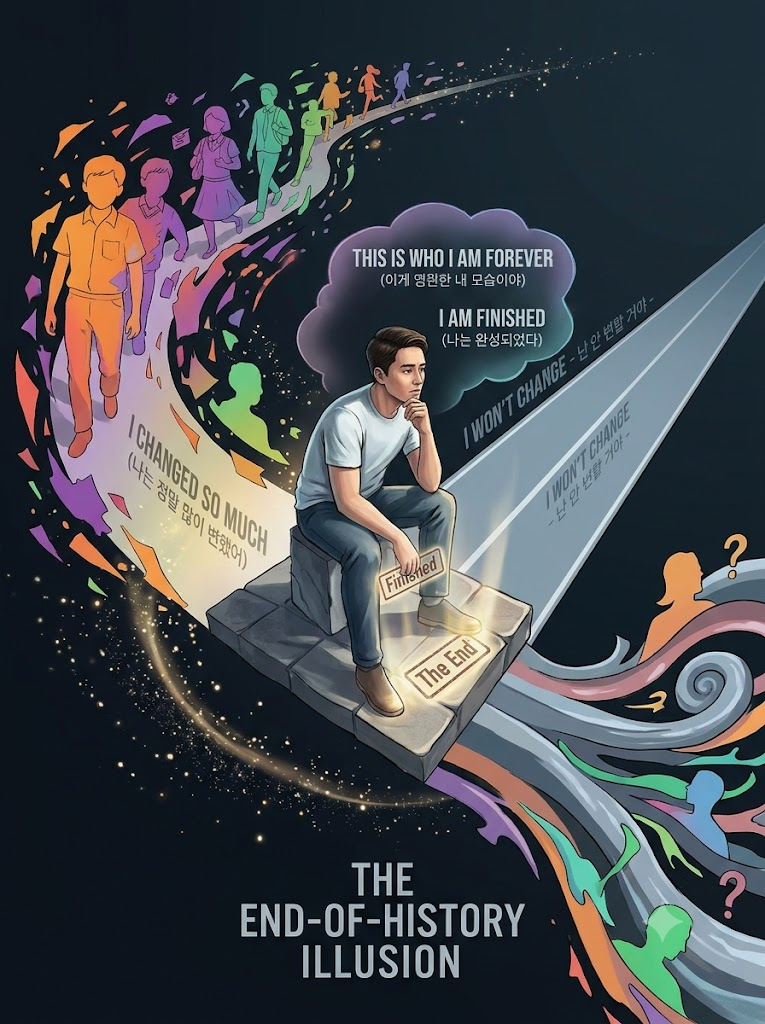
In financial planning, this illusion manifests as fixed goals like, “I will retire at 62 and live in this house forever.”
The possibility that the ‘you’ 10 years from now might want to move to the countryside or start a completely different career is left out of the equation from the start.
When you add the Sunk Cost Fallacy to this, you end up sticking to a path that no longer satisfies you because you don’t want to waste the time and money already invested. It is as if your past decisions are devouring your current options.
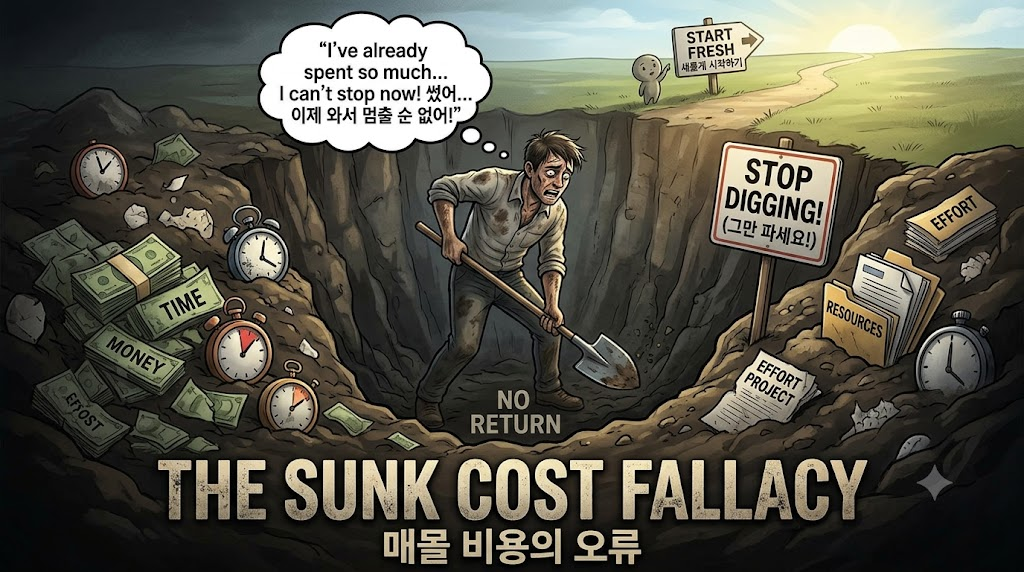
This is why the Barbell Strategy changes the question itself.** **
Instead of asking how well you can predict the future, it asks whether you can survive even if you’re wrong and profit from unexpected changes.
Fragile, Robust, and Antifragile: Where does your financial plan stand?
In his book Antifragile, Taleb categorizes how things react to shocks:
- Fragile: Breaks when shocked. Like a glass cup.
- Robust: Withstands shock but remains the same. Like a steel beam.
- Antifragile: Becomes stronger when shocked. Like muscles that grow stronger after exercise, or an immune system that creates antibodies after exposure to pathogens.
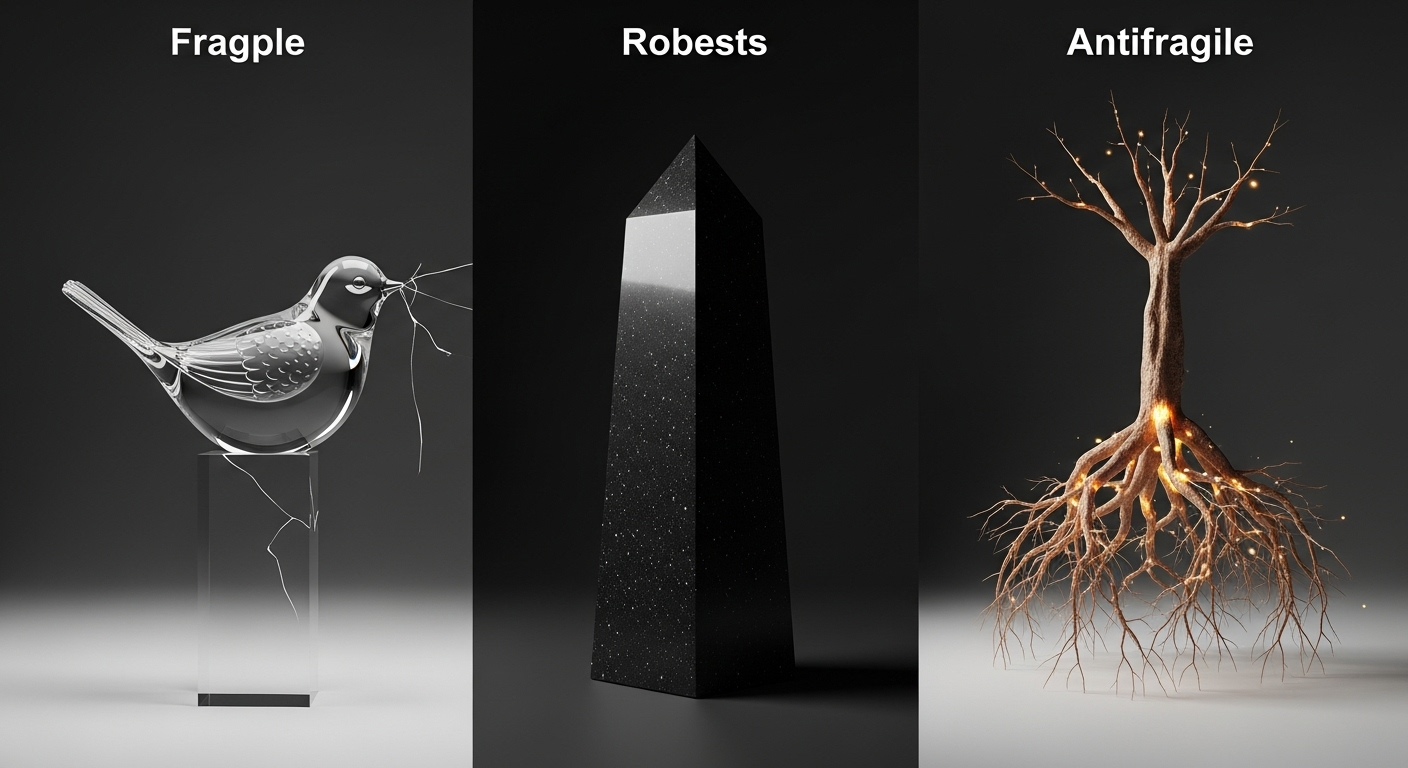
The question to evaluate your plan is simple.
What happens to your plan if you suddenly lose your job, the stock market drops 30%, or conversely, an unmissable opportunity arrives?
If your living expenses run out in a few months or you have no money to seize an opportunity, you are fragile.
If you can survive but cannot take advantage of opportunities, you are only robust.
If you can survive while still having the capacity to attempt something new, you are finally approaching antifragile.
Changing the purpose of savings: Buying back time with the Barbell Strategy
The safe end of the barbell does more than just secure retirement funds.
It is money that buys you optionality—the time to quit if your current job isn’t a fit and explore other paths. I find it more accurate to call this an ‘I changed my mind fund,’ as it allows you to pay the costs if the future ‘you’ decides to flip the script on your plans.
As Morgan Housel emphasizes in The Psychology of Money, the greatest dividend money pays is the control over your time to do what you want, when you want.
Whether you are wealthy or not is revealed less by your bank balance and more by whether you can say “no” to things you don’t want to do. I explored this perspective in detail in my posts on why a higher salary doesn’t guarantee happiness (‘Time Rich’) and the ‘Autonomy Premium’ of buying back your time with money.
Applying the Barbell Strategy to income sources and skills
While we often diversify our investment portfolios, we frequently put our biggest asset—our ’earning power’—into a single basket.
You can apply the barbell structure to your career as well.
- Income Sources: Keep your main job as the safe end, and one small side income as the aggressive end. More important than the amount is the fact that you have a buffer if your main job falters.
- Skills: Learn at least one skill far removed from your field of expertise. Think woodworking for a data analyst or coding for a marketer. Even if it doesn’t pay immediately, it becomes a bridge you can cross when the professional landscape changes.
Including small failures in your Barbell budget
Most bets at the aggressive end will fail. If you define this as an expense rather than a mistake, failure turns into information. Low-cost experiments like side projects, small investments, or new hobbies tell you what works and what doesn’t, even if they don’t succeed. This structure of losing small many times and winning big once follows the same logic as the principle that Amazon and Google used to embrace failure and succeed, “the tail wags the dog”.
Things to keep in mind when using the Barbell Strategy
When translating the Barbell Strategy into your actual accounts, consider these three points:
- Cash is also risky: The safe end has low risk of principal loss, but it is still vulnerable to inflation, which erodes its real value.
- The ratio is just an example: 85~90 / 10~15 is Taleb’s personal allocation. Depending on your income stability, dependents, and emergency fund size, it might be right for some to reduce the aggressive end to 5%.
- The key is emptying the middle ground: If you mix assets that ’look safe but are actually quite volatile’ into your safe end, it’s not a barbell. It is better to filter the safe side using objective criteria, such as the deposit insurance limit.
Returning to person A, what they needed wasn’t a more accurate list.
They needed a thick ‘safe end’ to protect their living expenses for 15 years, and a small ‘aggressive end’ to make new bets whenever their mind changed. If they had that structure, the 40-year-old A could have written a new list instead of just crossing out the old one.
Notice: This article is general information based on public data available at the time of writing and does not recommend buying or selling any specific stocks, assets, or financial products. The ratios are examples; please determine your actual allocation according to your individual situation. Systems such as deposit insurance limits may change in the future. (Last checked: 2026-10-25)
References
- The Black Swan: The Impact of the Highly Improbable
- “Antifragile: Things That Gain from Disorder” by Nassim Nicholas Taleb
- Quoidbach, J., Gilbert, D. T., & Wilson, T. D. (2013). The end of history illusion. Science, 339(6115), 96–98. https://doi.org/10.1126/science.1229294
- Financial Services Commission Press Release, Deposits protected up to 100 million KRW starting Sep 1, 2025 (2025-07-22). https://www.fsc.go.kr/edu/news/85077
- Morgan Housel, The Psychology of Money (2020)